Contact us
Contact Nuveen
Thank you for your message. We will contact you shortly.
Land-secured municipal bonds primarily finance essential infrastructure — roads, water and sewer lines, lighting — that supports real estate development. Often called “dirt bonds,” these securities are backed by property tax liens rather than general government revenue. Understanding their structure and regional dynamics is key to evaluating credit risk.
Key takeaways
- Land-secured bonds carry elevated risk at issuance but often improve as development completes and property ownership diversifies.
- California’s Mello-Roos structure and strict underwriting standards make it the most stable state market, with minimal distress.
- Colorado, Florida and Texas each show resilient housing demand and issuance growth, though affordability pressures warrant continued monitoring.
Land-secured bonds have specific financing structures
Land-secured bonds are usually issued through special taxing districts, which are independent governmental units that exist with varying degrees of administrative and fiscal independence from local governments.
Laws governing these bonds differ by state, but structures, security features and issuance procedures share many similarities. Fundamentally, a land-secured bond works like this:
Within the taxing district, a tax lien is placed on property benefiting from the public infrastructure built with bond proceeds. This lien is paid off over time through periodic assessments or taxes.
Assessment or tax revenues pay debt service on the bonds. This lien is senior to any mortgage on the property.
The basic bond structures include:
Special tax districts. Bonds are secured and payable by an annual tax levied on district property. The tax must be reasonable but may shift based on project costs, tax collections and other variables.
Special assessment districts. Bonds are secured by a lien based on formulas that measure how much each property benefits from the funded improvement. The lien is usually a fixed amount.
Limited tax districts. Bonds are secured by an annual limited ad valorem tax capped at a not-to-exceed rate. It is determined by the amount of reimbursable public infrastructure costs, along with the district’s ability to pay debt service. The district’s assessed value must reach a certain level to generate sufficient revenue for debt service.
Sector status is mixed
Land-secured bonds are generally viewed as higher-risk at issuance, but risks may decline as development progresses and taxpayer diversity increases.
Sector risks
Development risk. Until a project is fully built out, all land-secured bonds carry some development risk. In troubled markets, projects can stall or be abandoned, potentially leading to default.
Potentially high leverage. Some bonds carry high leverage. For example, a value-to-lien ratio of just 2:1 at issuance means land value is only twice the debt issued. If undeveloped property value falls below its allocated debt, owners have little incentive to pay special taxes.
Taxpayer concentration. Investors may face long-term
exposure to a single developer or small group of developers
— a risk that grows when development slows.
Sector strengths
Significant absorption. When development is complete or near-complete, bond issues often feature diversified tax bases and strong collateral coverage. These characteristics generally support investment grade quality.
Potential credit improvement. Land-secured bonds typically issue nonrated due to the risks above. As development matures and ownership diversifies, the tax burden shifts from concentrated to broad-based — often earning these bonds an investment grade rating over time.
California’s market holds steady
California’s land-secured market has stayed relatively stable for a decade. Per Bloomberg, the state has $15.8 billion in outstanding land-secured bonds, with only 1.9% classified as distressed.
Most California land-secured bonds are Community Facilities District (CFD) bonds issued under the Mello-Roos Act of 1982. Given this mechanism’s long history and strict underwriting requirements, CFD bonds have historically seen less distress than structures in other states. A key strength: California requires a 3:1 value-to-lien ratio on all new bonds, meaning property value must equal or exceed attached debt by at least three times.
Issuance was solid in 2025 at roughly $2.8 billion, up about $460 million year-over-year. Through August 2026, issuance reached $1.8 billion — suggesting the year will land between 2024 and 2025 levels.
California’s housing market remains highly competitive as demand outpaces new supply, pushing costs higher. In May, the median single-family home price hit an all-time high of $930,000, up 2.2% year-over-year.
Given the state’s housing shortage, Governor Newsom recently signed reforms to streamline affordable housing construction. Homebuilders are expected to capitalize on these changes to help close the supply gap.
Strong economic conditions and limited coastal land have driven homebuilding activity inland. Large-scale projects like “The Great Park” in Irvine and “Westpark” in Roseville continue seeing strong demand, while developers increasingly target less populated regions like the Central Valley to address affordability.
Colorado growth slows but persists
Most Colorado land-secured bonds are issued through Metropolitan Districts (MDs) and paid from a limited ad valorem tax. Since most districts are residential, credit quality — particularly in early-stage districts — closely tracks housing market strength, as new construction and valuation build the tax base supporting repayment.
Home prices nationally and in Colorado rose sharply during the pandemic, driven by low rates and remote work demand. Per the S&P Cotality Case-Shiller Denver Index, Denver home prices climbed 54% from January 2019 to June 2022 (the 20-city national index rose 50% over the same period). Since peaking, Denver prices have declined 4.6% through May 2026 and 1.7% year-over-year. The national index has stabilized, up 2.4% annually since June 2022 and 1.6% year-over-year through May.
Issuance grew significantly in recent years before dipping in 2023 amid the housing slowdown and higher rates. Volume grew from under $100 million annually post recession to over $1 billion in 2018, a record $2 billion in 2021 and $1.7 billion in 2022. Issuance fell to $558 million in 2023, rebounded to $1.8 billion in 2024 and finished just under $2 billion in 2025. Through June 2026, issuance is flat year-over-year at approximately $870 million. We expect issuance to pick up in the second half as 2021-issued bonds approach their five-year call date, likely returning volume to the $2 billion range.
Population growth along the Front Range remains the primary driver of home construction and credit quality. Growth averaged 1.5% annually from 2010 to 2020, slowing to roughly 0.8% since 2020 — still positive and meaningful in absolute terms.
Favorable demographics continue supporting Colorado’s housing market and land-secured credit quality. The main concern is affordability amid persistently high mortgage rates. Building permits in Denver peaked during the 2021 building boom and have since trended toward pre pandemic levels, declining roughly 3% year-over-year through May 2026.
Existing home sales remain below historical averages as low-rate mortgage holders stay put, pushing buyers toward new construction — supporting credit quality for MD bonds, especially in early-stage districts.
Florida’s population trends support issuance
Florida land-secured bonds, known as Community Development Districts (CDDs), are secured by annual assessments on planned lots through bond maturity. Developers use these bonds to finance infrastructure and create lots for new construction.
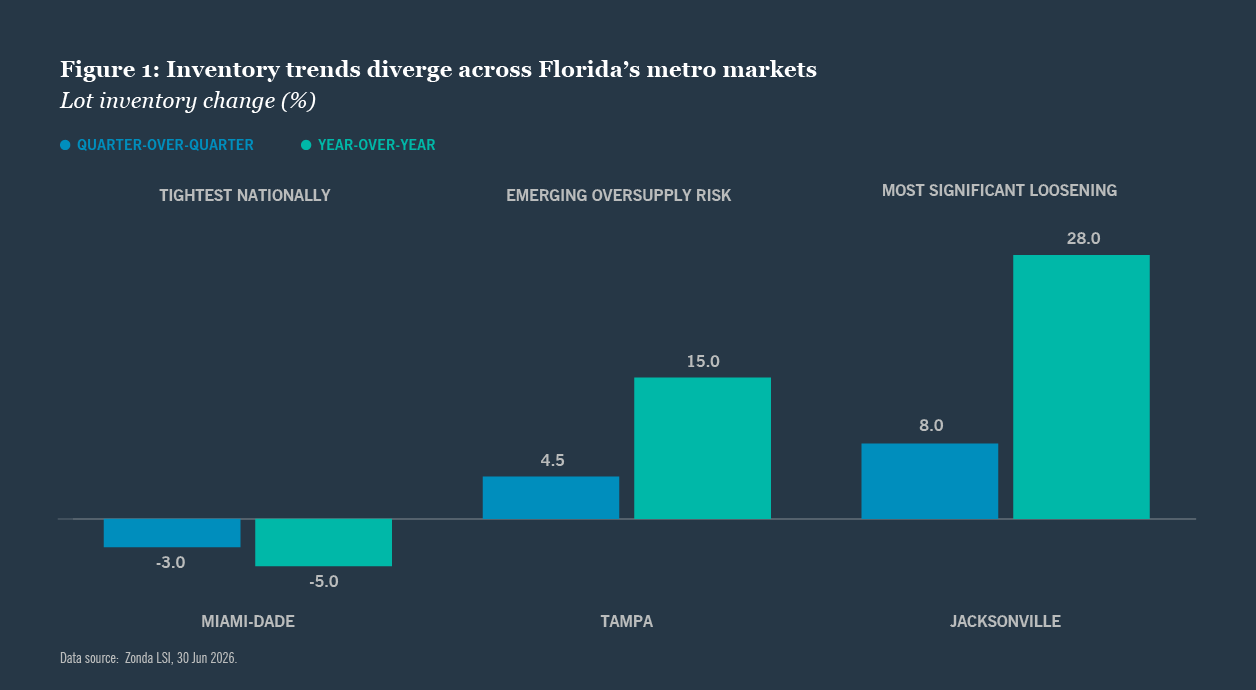
Florida’s new home demand has relied heavily on population growth, which has cooled sharply since the pandemic boom (310,892 new residents in 2022 versus just 22,517 in 2025). Still, demand remains resilient in actively selling communities, with tighter markets like Miami showing signs of stabilization (Figure 1). This shift has increased inventory and pricing pressure as builders adjust. Lot inventories, product positioning and affordability all warrant close monitoring.
Elevated mortgage rates and high home prices continue creating affordability barriers in high-demand markets. Builders have responded with discounts and incentives — including credits and rate buydowns — to maintain sales momentum while continuing to develop inventory ahead of anticipated rate declines.
Larger homebuilders are using strong balance sheets to sustain construction, adjust pricing strategically and offer buyer incentives. We expect these well-capitalized builders to keep gaining market share, positively impacting construction pace and sales velocity within master-planned communities where we maintain exposure. Per RCLCO, Florida hosted 10 of the nation’s top 50 master-planned communities in 2025.
Florida CDD bonds continue showing remarkable strength. New money volume totaled $1.96 billion in 2025, just behind 2024’s record $2 billion, with total volume from 2020-2025 exceeding $8.85 billion. The market saw 135 new money transactions in 2025 averaging roughly $14.5 million each. Developers established 56 new CDDs, directing growth toward inland markets like Ocala and Lakeland. Including refundings, total 2025 volume surpassed $2.0 billion — marking the tenth consecutive year Florida CDD tax-exempt volume has exceeded $1 billion.
Texas cools while fundamentals stay solid
Texas land-secured bonds, structured as Public Improvement Districts (PIDs), are secured by annual assessments on planned lots through bond maturity. The sector has grown meaningfully, with issuance exceeding $3.4 billion in 2021-2025, including nearly $1.2 billion in 2025. Growth continued in 2026, with 41 issuances totaling $486.8 million through July 30. We expect further expansion supported by continued population growth.
The Dallas-Fort Worth Metroplex continues dominating the Texas PID market, representing 75% of 2025 issuance, 71% in 2024 and 80% in 2023. Austin has gained share too, at 16% in 2025, 15% in 2024 and 19% in 2023. We expect Houston and San Antonio to become more meaningful contributors: Houston represented 8% of 2025 issuance.
Population growth remains the primary demand driver. Texas led the nation in net domestic migration, adding an estimated 300,000 residents from July 2022 through July 2025, though annual migration fell sharply from its 2022 peak to 67,000 in the most recent year. International migration added an estimated 320,000 residents in 2024 before declining 48% to 167,475 in 2025. Despite rising resale inventory, new homes continue benefiting from builder tools unavailable in resale markets — upgrades and rate buydowns that improve affordability and attract buyers.
Nuveen closely monitors housing inventory, available supply, vacant developed lots and home prices. Active for-sale inventory in DFW reached nearly 30,000 units as of July 2026 — down year-over-year but still elevated historically. The Case-Shiller Dallas Home Price Index declined 0.7% over the past year and rose just 0.7% over three years, though prices remain up 80% over the decade.
Austin inventory has stayed relatively stable, with 13,245 active listings in June 2026 versus 13,105 in June 2025 and 13,227 in June 2024 — still more than double the 6,282 listings seen in 2019. Austin prices peaked in Q2 2022 and have since declined 12% per the Austin-Round Rock Georgetown House Price Index. Even so, prices remain up 80% over the past decade.
Land-secured deals warrant a closer look
Well-structured land-secured deals can offer investors strong collateral and warrant consideration on a case-by-case basis.
California’s “dirt bond” market benefits from the solid security structure of Mello-Roos bonds. Despite repayment concerns, just 2% of the state’s $14.4 billion in outstanding bonds are classified as distressed.
Colorado’s risk profile is similar to Florida’s, with affordability remaining a concern. Still, favorable demographics and fundamentals continue supporting this market.
Florida carries a higher risk profile than California. However, recent issuances feature smaller sizes, fewer planned lots and lower leverage — suggesting better resilience than pre-2008 crisis structures.
In Texas, Nuveen expects total issuance to approach or exceed $1 billion this year. While Texas PID deals carry more risk than California issues, we view them as less risky than Colorado or Florida given stronger local government oversight and assessments that exceed debt service requirements.
Evaluating land-secured municipal bonds demands deep knowledge of individual credits and local markets. Three factors matter most: location, development group strength and collateralization — the land value relative to issued debt. Disciplined analysis paired with awareness of broader macroeconomic trends is essential to assessing this sector.
Related articles
Positive risk sentiment buoys Treasury yields

Tax-loss harvesting: Upgrade portfolios amidst volatility
Rates climb again: Is the muni opportunity still intact?
Related articles
Tax-loss harvesting: Upgrade portfolios amidst volatility
Rates climb again: Is the muni opportunity still intact?
Rate spike creates a compelling entry point for municipals
About the author

Contact us
You are on the site for: Financial Professionals and Individual Investors. You can switch to the site for: Institutional Investors or Global Investors
Endnotes
Sources
New Construction Data and New Household Formation statistics: FRED; California: Bloomberg and California Association of Realtors; Florida: MBS Capital Markets for new issuance data; Colorado: S&P Case-Shiller for the home price appreciation, Bloomberg for the issuance data, and https:// worldpopulationreview.com/states for the population data.
This material is not intended to be a recommendation or investment advice, does not constitute a solicitation to buy, sell or hold a security or an investment strategy, and is not provided in a fiduciary capacity. The information provided does not take into account the specific objectives or circumstances of any particular investor, or suggest any specific course of action. Investment decisions should be made based on an investor’s objectives and circumstances and in consultation with his or her financial professionals.
The views and opinions expressed are for informational and educational purposes only as of the date of production/writing and may change without notice at any time based on numerous factors, such as market or other conditions, legal and regulatory developments, additional risks and uncertainties and may not come to pass. This material may contain “forward-looking” information that is not purely historical in nature. Such information may include, among other things, projections, forecasts, estimates of market returns, and proposed or expected portfolio composition. Any changes to assumptions that may have been made in preparing this material could have a material impact on the information presented herein by way of example. Performance data shown represents past performance and does not predict or guarantee future results. Investing involves risk; principal loss is possible.
All information has been obtained from sources believed to be reliable, but its accuracy is not guaranteed. There is no representation or warranty as to the current accuracy, reliability or completeness of, nor liability for, decisions based on such information and it should not be relied on as such. For term definitions and index descriptions, please access the glossary on nuveen.com. Please note, it is not possible to invest directly in an index.
Important information on risk
Investing involves risk; principal loss is possible. All investments carry a certain degree of risk and there is no assurance that an investment will provide positive performance over any period of time. Investing in municipal bonds involves risks such as interest rate risk, credit risk and market risk. The value of the portfolio will fluctuate based on the value of the underlying securities. There are special risks associated with investments in high yield bonds, hedging activities and the potential use of leverage. Portfolios that include lower rated municipal bonds, commonly referred to as “high yield” or “junk” bonds, which are considered to be speculative, the credit and investment risk is heightened for the portfolio. Bond insurance guarantees only the payment of principal and interest on the bond when due, and not the value of the bonds themselves, which will fluctuate with the bond market and the financial success of the issuer and the insurer. No representation is made as to an insurer’s ability to meet their commitments.
This information should not replace an investor’s consultation with a financial professional regarding their tax situation. Nuveen is not a tax advisor. Investors should contact a tax professional regarding the appropriateness of tax-exempt investments in their portfolio. If sold prior to maturity, municipal securities are subject to gain/losses based on the level of interest rates, market conditions and the credit quality of the issuer. Income may be subject to the alternative minimum tax (AMT) and/or state and local taxes, based on the state of residence. Income from municipal bonds held by a portfolio could be declared taxable because of unfavorable changes in tax laws, adverse interpretations by the Internal Revenue Service or state tax authorities, or noncompliant conduct of a bond issuer. It is important to review your investment objectives, risk tolerance and liquidity needs before choosing an investment style or manager.
Nuveen, LLC provides investment solutions through its investment specialists.
This information does not constitute investment research as defined under MiFID
Not registered yet? Register