Contact us
Contact Nuveen
Thank you for your message. We will contact you shortly.

Split? Sweep? Status quo? Every seat in the U.S. House of Representatives and roughly one-third of seats in the U.S. Senate are being contested this November. A divided Congress, with Democrats flipping the House and Republicans holding the Senate, is our base case scenario. This outcome would likely push policymaking further toward executive action versus legislation, and heighten risks around budget negotiations, funding deadlines and the debt ceiling — a perennial struggle that will need to be addressed again as early as 2027. Because both political parties have historically added to federal debt to a similar degree, a sweep by either party would potentially produce the largest proposed fiscal spending.
Regarding geopolitical issues, Iran currently has little incentive to negotiate ahead of the U.S. election. That said, if U.S. public opinion against the war — and the surge in oil prices fueling broader inflation anxiety — puts pressure on the Trump administration to forge a hurried deal before Election Day, the terms could end up being more favorable to Iran.
Beyond fiscal policy, inflation and geopolitics, voter decisions could also hinge on concerns about AI broadly and the AI infrastructure buildout in particular. Local opposition to data centers, centered on electricity and water use, have already prompted bipartisan support for building moratoriums and ratepayer protections.
Gauging the possible impacts of Election Day on financial markets. Regardless of the specific election outcome and initial investor response, history suggests that markets typically move back to normal trading patterns relatively quickly after results are known. In fact, equity returns have often been stronger than average over the following year post-election, except during periods of unusual or systemic financial stress. Absent greater bipartisan discipline on budgetary matters, we expect the bond market to remain a marker for fiscal health, especially amid the current selloff in U.S. Treasuries and recent intervention by the Treasury Department to contain rising yields via aggressive debt buybacks.
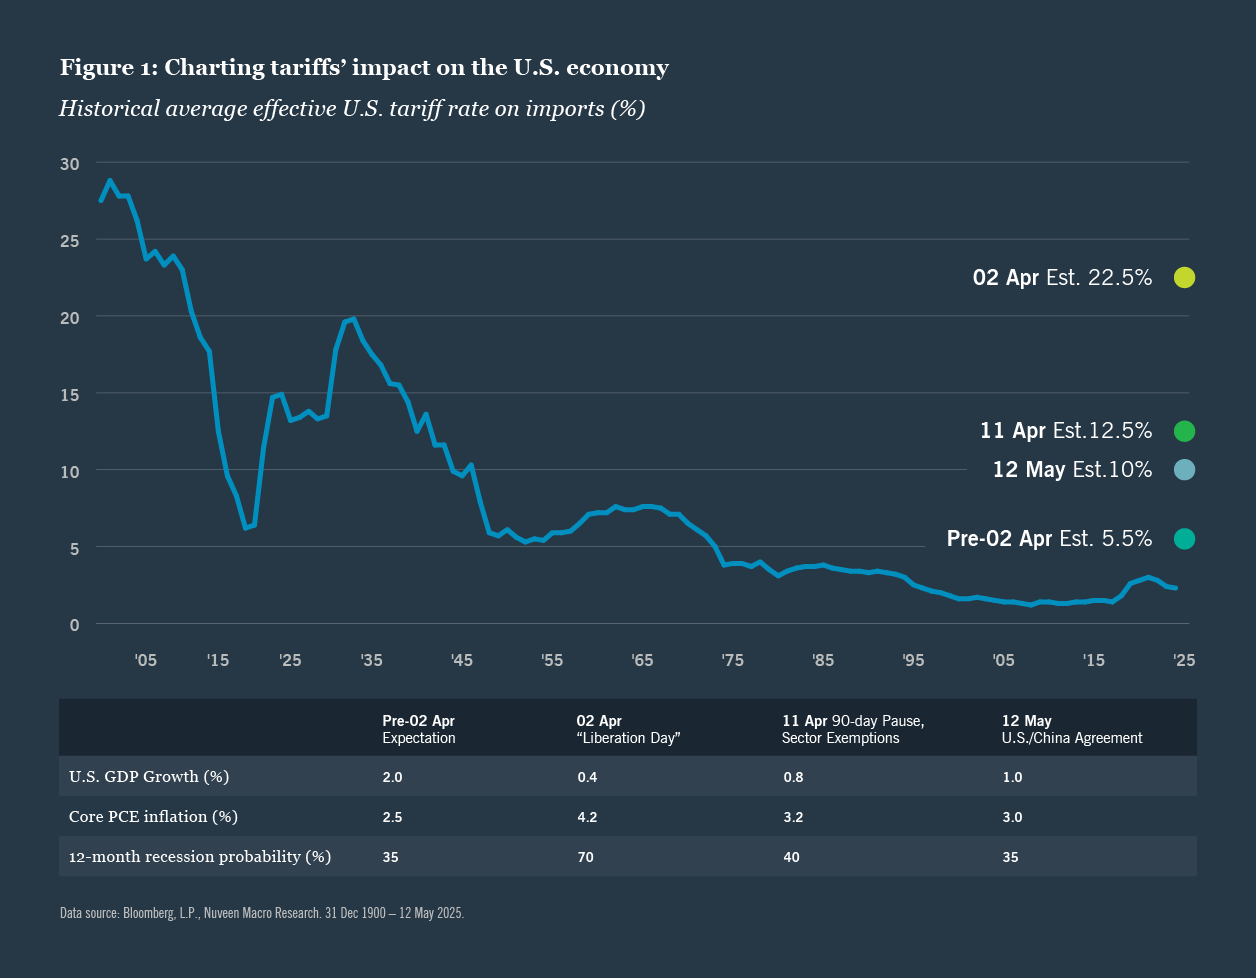
As for equities, the second year of a presidential term has historically tended to be the weakest for returns, with market volatility peaking ahead of the vote before fading. Figure 1 shows that under a House-flips-to-Democrats/Senate-stays- Republican scenario, the S&P 500 Index has returned +11.95%, on average, over the six months following midterm elections. Over the long term, stock markets have generally risen, sometimes unevenly, regardless of which party holds the reins in Washington, D.C.
While markets can be more volatile in advance of elections, history suggests they resume more normal trading patterns once results are known.
Portfolio considerations
Midterm election years tend to bring below-average equity returns and higher market volatility, with the S&P 500 underperforming early in the year compared to a typical nonmidterm year. Moreover, divided or narrow majorities are likely to dampen the prospects for major legislation over the next two years.
We think a split Congress outcome (Democratic House/Republican Senate) would diminish potential consensus and lead to divergence across key areas: a Republican Senate that continues to shield banks and credit cards from rate caps and fee regulation, while promoting defense spending and deregulation, countered by a Democratic House safeguarding life sciences funding and pushing for compromise on infrastructure issues, particularly around rails, broadband and water. Permitting reforms for liquefied natural gas and renewable energy sources may be a point of bipartisan agreement given rising data center power demand. These mixed possibilities reinforce that midterm outcomes are best understood as a sector- and industry-level dynamic rather than a broad market signal.
Historically, midterm elections have not been a reliable signal for bond markets. Over the past 16 midterms, the 10-year U.S. Treasury yield has fallen by an average of more than 30 basis points (bps) in the year after a president’s party lost control of at least one legislative chamber, compared with an average increase of nearly 60 bps when it retained control. The range of outcomes, however, has been wide.
The associated checks and balances implicit in a divided government could be reassuring to bond investors. Tempered expectations for expanded fiscal spending, for example, may ease some pressure on the long end of the Treasury curve. But gridlock would still leave large deficits, and rising government debt could keep upward pressure elevated for Treasury yields.
Beyond Treasuries, our constructive view on corporate credit is supported by resilient economic growth, although higher refinancing costs lead us to be selective in the high yield space. In securitized categories, bouts of rate-driven volatility can create better entry points in areas where underlying fundamentals remain sound. Municipal bonds are more directly exposed to the election through potential tax and spending policy changes, while floating rate credit still offers attractive income. Overall, fixed income assets continue to offer historically elevated yields, which create potentially attractive entry points (Figure 2).
Election outcomes could affect different industries and sectors for good or ill, but are unlikely to be a driver of broad market trends.

Nuveen’s Global Investment Committee (GIC) brings together the most senior investors from across our platform of core and specialist capabilities, including all public and private markets.
Regular meetings of the GIC lead to published outlooks that offer:
- macro and asset class views that gain consensus among our investors
- insights from thematic “deep dive” discussions by the GIC and guest experts (markets, risk, geopolitics, demographics, etc.)
- guidance on how to turn our insights into action via regular commentary and communications
Related articles

Bond markets reel from September’s sharp selloff
The Fed dishes a dose of tightening

CIO commentary archive
About the author
Contact us
You are on the site for: Financial Professionals and Individual Investors. You can switch to the site for: Institutional Investors or Global Investors
Endnotes
Sources
All market and economic data from Bloomberg, FactSet and Morningstar.
This material is not intended to be a recommendation or investment advice, does not constitute a solicitation to buy, sell or hold a security or an investment strategy, and is not provided in a fiduciary capacity. The information provided does not take into account the specific objectives or circumstances of any particular investor, or suggest any specific course of action. Investment decisions should be made based on an investor’s objectives and circumstances and in consultation with his or her financial professionals.
The views and opinions expressed are for informational and educational purposes only as of the date of production/writing and may change without notice at any time based on numerous factors, such as market or other conditions, legal and regulatory developments, additional risks and uncertainties and may not come to pass. This material may contain “forward-looking” information that is not purely historical in nature.
Such information may include, among other things, projections, forecasts, estimates of market returns, and proposed or expected portfolio composition. Any changes to assumptions that may have been made in preparing this material could have a material impact on the information presented herein by way of example. Performance data shown represents past performance and does not predict or guarantee future results. Investing involves risk; principal loss is possible.
All information has been obtained from sources believed to be reliable, but its accuracy is not guaranteed. There is no representation or warranty as to the current accuracy, reliability or completeness of, nor liability for, decisions based on such information and it should not be relied on as such. For term definitions and index descriptions, please access the glossary on nuveen.com. Please note, it is not possible to invest directly in an index.
Important information on risk
All investments carry a certain degree of risk and there is no assurance that an investment will provide positive performance over any period of time. Equity investments are subject to market risk, active management risk, and growth stock risk; dividends are not guaranteed. Non-U.S. investments involve additional risks, including currency fluctuation, political and economic instability, lack of liquidity and differing legal and accounting standards. These risks are magnified in emerging markets. Debt or fixed income securities are subject to market risk, credit risk, interest rate risk, call risk, tax risk, political and economic risk, and income risk. As interest rates rise, bond prices fall. Credit risk refers to an issuer’s ability to make interest payments when due. Below investment grade or high yield debt securities are subject to liquidity risk and heightened credit risk. Senior loans may not be fully secured by collateral, generally do not trade on exchanges, and are typically issued by unrated or below-investment grade companies, and therefore are subject to greater liquidity and credit risk. There are special risks associated with investing in preferred securities, including generally an absence of voting rights with respect to the issuing company unless certain events occur. Also in certain circumstances, an issuer of preferred securities may redeem the securities prior to a specified date. As with call provisions, a redemption by the issuer may negatively impact the return of the security held by an account. In addition, preferred securities are subordinated to bonds and other debt instruments in a company’s capital structure and therefore will be subject to greater credit risk than those debt instruments. Investing in municipal bonds involves risks such as interest rate risk, credit risk and market risk, including the possible loss of principal. The value of the portfolio will fluctuate based on the value of the underlying securities. There are special risks associated with investments in high yield bonds, hedging activities and the potential use of leverage. Portfolios that include lower rated municipal bonds, commonly referred to as “high yield” or “junk” bonds, which are considered to be speculative, the credit and investment risk is heightened for the portfolio. Credit ratings are subject to change. It is important to review your investment objectives, risk tolerance and liquidity needs before choosing an investment style or manager.
Nuveen, LLC provides investment services through its investment specialists.
CFA® and Chartered Financial Analyst® are registered trademarks owned by CFA institute.
This information does not constitute investment research as defined under MiFID.
Not registered yet? Register