Contact us
Contact Nuveen
Thank you for your message. We will contact you shortly.

Has bad news become bad news again? Recent upside inflation surprises have complicated the outlook for U.S. Federal Reserve policy, with rising energy costs and persistent price pressures threatening to prolong restrictive monetary policy. Yet after climbing sharply in the third quarter, U.S. Treasury yields have been trending lower in October. The bellwether 10-year yield ended last week at 5.09%, down -22 basis points (bps) from the multidecade high of 5.31% on 05 October. Concerns about economic growth, weakening manufacturing demand and the sustainability of surging capital investment in AI have contributed to easing yields.
Inflation dominated last week’s economic calendar. Headline Consumer Price Index (CPI) accelerated in September to an above-forecast 3.7% year-over-year, up from 3.4% in August, driven largely by rising gasoline and fuel oil costs. Core CPI, which excludes volatile food and energy prices, also exceeded expectations, suggesting price pressures may prove more persistent than anticipated. Meanwhile, wages haven’t kept pace: Average hourly earnings growth was essentially flat at +0.1% month-over-month in September, missing expectations by 0.2% (Figure 1).
The Producer Price Index (PPI) reinforced inflation anxiety, rising 1.3% month over-month — more than double consensus estimates and the largest monthly increase since March 2022. Year-over-year PPI jumped to 6.3% from 5.6%, sparking concern that businesses may increasingly choose to pass costs on to consumers rather than risk narrower margins by absorbing them.
The Philadelphia Fed Manufacturing Index added to the complex backdrop, with the headline print for October well below expectations, dropping to 20.9 from 37.8. The new orders component plunged nearly 25 points to 4.3, signaling a meaningful demand slowdown. In contrast, the prices received index rose to 40.1, its highest since May 2025. The net result: a potentially stagflationary mix of slowing growth and persistent inflation — and a difficult balancing act for policymakers.
Earnings season kicks off under cloudy skies. With the Fed facing competing signals from inflation and economic activity, the key macro question for markets is whether growth can remain resilient without requiring a further tightening of financial conditions. Next week’s relatively light economic calendar may not provide many answers, so investor focus will shift to third quarter earnings. Among the anticipated insights are the state of corporate margins, underlying demand and AI related capital expenditures (capex). The AI trade has come under renewed pressure of late, with scrutiny on infrastructure financing and some “neocloud” debt issues reaching speculative-grade yields.
As a result, fundamentals such as earnings quality, balance-sheet strength and valuation discipline will be top of mind. Portfolio decisions, in turn, should be guided by diversification, selectivity and identifying companies capable of sustaining earnings growth.
Recent inflation surprises have complicated the outlook for U.S. Federal Reserve policy.

Portfolio considerations
The opening bell has rung on third quarter earnings season for the S&P 500 Index, with big banks claiming the spotlight before other sectors take the stage. Last week, markets were eager to hear how major financial firms would characterize the impact of higher interest rates. Bank earnings results pointed to steady consumer credit trends outweighing a slowdown in trading and dealmaking activity, while forward guidance on net interest margins and credit conditions should serve as an early signal for the rest of the season.
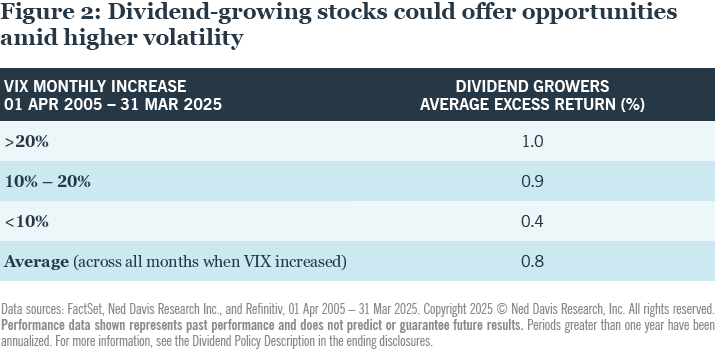
Looking ahead, FactSet projects the overall index will ultimately report year-over year earnings growth above +35% for Q3 — higher than the current estimate of 29.0% (Figure 2), based on the recent tendency for growth rates to climb as more companies post positive surprises. For 2026 as a whole, analysts now forecast earnings growth of +32.8%, up slightly from the +32.4% estimate on 30 June. This pace is expected to decelerate sharply, to +16.0%, in 2027.
The outlook for tech earnings commands particular attention given the AI buildout. Information technology is expected to deliver earnings growth of +65.1% for the quarter, second only to energy (an estimated +127.6%) among the index’s 11 sectors. Within technology, semiconductors are the single-largest driver, with earnings projected to surge +130%; without semis, sector growth would be +24.4%. Such concentration echoes a broader dynamic: the Magnificent 7 stocks are expected to produce earnings growth of roughly +33.2%, versus +27.7% for the other 493 companies in the index. Within the Magnificent 7, two companies — NVIDIA and Meta — will likely account for an overwhelming majority of the group’s earnings growth, a narrow base worth monitoring.
Considering the healthy anticipated growth in earnings per share (EPS), we believe valuations are reasonable. The S&P 500’s forward price-to-earnings (P/E) multiple of 19.0x is lower than its 5-year average of 19.8x and generally in line with its 10-year average of 19.1x, aided by EPS estimates that since June have risen faster than prices.
While bank earnings are being watched for inflation’s impact, IT sector earnings command particular attention amid the ongoing AI buildout.
Nuveen’s Global Investment Committee (GIC) brings together the most senior investors from across our platform of core and specialist capabilities, including all public and private markets.
Regular meetings of the GIC lead to published outlooks that offer:
- macro and asset class views that gain consensus among our investors
- insights from thematic “deep dive” discussions by the GIC and guest experts (markets, risk, geopolitics, demographics, etc.)
- guidance on how to turn our insights into action via regular commentary and communications
Related articles
Investors retreat to safety as AI stumbles
The Fed dishes a dose of tightening

CIO commentary archive
About the author
Contact us
You are on the site for: Financial Professionals and Individual Investors. You can switch to the site for: Institutional Investors or Global Investors
Endnotes
Sources
All market and economic data from Bloomberg, FactSet and Morningstar.
This material is not intended to be a recommendation or investment advice, does not constitute a solicitation to buy, sell or hold a security or an investment strategy, and is not provided in a fiduciary capacity. The information provided does not take into account the specific objectives or circumstances of any particular investor, or suggest any specific course of action. Investment decisions should be made based on an investor’s objectives and circumstances and in consultation with his or her financial professionals.
The views and opinions expressed are for informational and educational purposes only as of the date of production/writing and may change without notice at any time based on numerous factors, such as market or other conditions, legal and regulatory developments, additional risks and uncertainties and may not come to pass. This material may contain “forward-looking” information that is not purely historical in nature.
Such information may include, among other things, projections, forecasts, estimates of market returns, and proposed or expected portfolio composition. Any changes to assumptions that may have been made in preparing this material could have a material impact on the information presented herein by way of example. Performance data shown represents past performance and does not predict or guarantee future results. Investing involves risk; principal loss is possible.
All information has been obtained from sources believed to be reliable, but its accuracy is not guaranteed. There is no representation or warranty as to the current accuracy, reliability or completeness of, nor liability for, decisions based on such information and it should not be relied on as such. For term definitions and index descriptions, please access the glossary on nuveen.com. Please note, it is not possible to invest directly in an index.
Important information on risk
All investments carry a certain degree of risk and there is no assurance that an investment will provide positive performance over any period of time. Equity investments are subject to market risk, active management risk, and growth stock risk; dividends are not guaranteed. Non-U.S. investments involve additional risks, including currency fluctuation, political and economic instability, lack of liquidity and differing legal and accounting standards. These risks are magnified in emerging markets. The use of derivatives involves additional risk and transaction costs. It is important to review your investment objectives, risk tolerance and liquidity needs before choosing an investment style or manager.
Nuveen, LLC provides investment services through its investment specialists.
CFA® and Chartered Financial Analyst® are registered trademarks owned by CFA institute.
This information does not constitute investment research as defined under MiFID.
Not registered yet? Register