The plan sponsor playbook : How to meet participants where they are on the road to retirement income
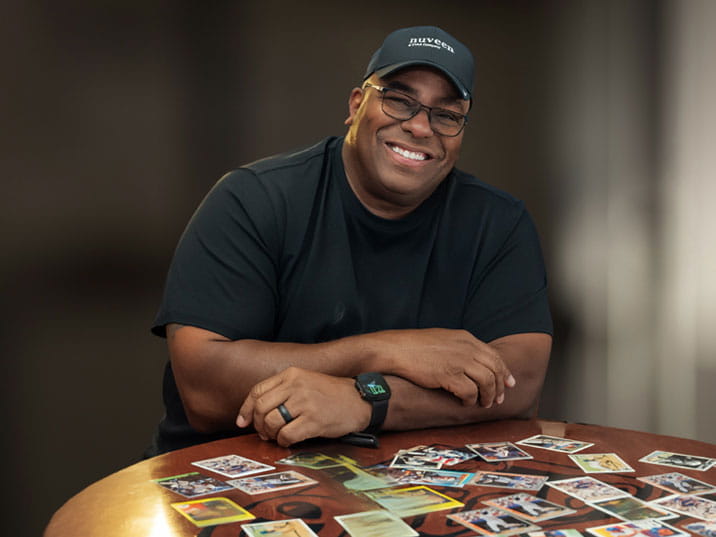
Every July, Bobby Bonilla receives a seven-figure check from the New York Mets, even though he last played for the team in 1999. The payment comes from a contract he agreed to defer decades ago. The appeal is easy to understand.
Helping employees understand retirement income has never been easy. As guaranteed income options become more widely available in defined contribution plans, sponsors face a harder challenge: helping participants understand how guaranteed income could fit into their retirement plan well before they need to make a decision.
Key takeaways
- A simple story does what a product brochure cannot. Bobby Bonilla’s deferred-income deal explains guaranteed income in seconds, delivering the comprehension that participant education on annuities has been missing.
- The retirement journey has stages, and education should follow them. Planting income concepts early, reinforcing them mid-career, and reframing at late career gives participants time to understand their options before the decision turns urgent.
- Education belongs inside plan design. Sponsors who see real engagement build participant literacy into how the plan works. Without a framework for turning savings into income, even the strongest product lineup falls flat.
A guaranteed stream of payments, in one story
Every first of July, Bobby Bonilla gets a check from the New York Mets for $1,193,248.20, despite having last played for them in 1999. He will keep getting it until 2035, when he turns 72, by which point a $5.9 million buyout negotiated in 2000 will have paid him $29.8 million.13
Most people who hear the story see the value immediately. Defer the money, let it compound, receive a predictable stream of payments over decades, without direct market exposure. That is what guaranteed income can feel like when it is built into plan design and working as intended. The trouble is that most retirement savers have never been given a way to picture it that clearly.
Plan sponsors now have a wide range of tools to make that income real for employees. SECURE 2.0 clarified or removed a number of administrative barriers to adding lifetime income options, and in September 2025 the DOL issued guidance opening a path for lifetime income solutions to qualify as default investment alternatives. Recordkeeper availability has expanded sharply: 77% of recordkeepers now offer at least one annuity product, and fixed index annuity availability has more than doubled since 2024.14 Three in four DC plan sponsors expect demand for in-plan annuities to grow significantly over the next five years.15
More retirement income solutions are available today than ever before. The regulatory runway is positive, and participants want lifetime income in their retirement plans (see our Participant Perspectives article in this edition of next). What remains is the work of helping them visualize the role lifetime income plays across the retirement journey. Moving from saving to spending is a genuinely difficult transition, and breaking it into something easy to conceptualize is a challenge many sponsors and their advisors have yet to solve.
Retirement as a series of decisions
Retirement can be overwhelming for participants because, frankly, they probably haven’t done it before. What income sources do I have? In what order do I draw them? What are the tax implications? How much can I spend? What happens if I live longer than planned? How do I protect against a bad market in the first years of retirement? Every one of these is its own education challenge, often involving a range of advisors. For employees, simply knowing which question to address first, while also navigating the emotional shift from working life to retired life, can be a significant hurdle.
The sponsors getting this right treat each stage of the journey as its own education moment. Instead of a single retirement communication, they build a sequence across the working career that raises the complexity of the material over time and surfaces the relevant decision at each point.
The instinct across financial services is to front-load employees with disclosures and materials so that everything they might need to know is immediately available. It can be far more productive to treat the first explanation as an entry point. Behavioral research bears this out: a 2025 NBER study found that when participants could see a guaranteed income decision in the context of their broader retirement picture, rather than as a standalone product choice, take-up increased substantially.16 The barrier was framing that overcomplicated the picture. As participants grow more familiar with lifetime income, complexity can be layered in over time, deepening understanding and leading to better-informed outcomes.
Sponsors can build this progression into how they sequence participant communication across the career journey:
-
EARLY CAREER
Anchor on the concept
A 28-year-old doesn’t need to know the mechanics of a fixed annuity. Plan sponsors need to help employees understand that retirement savings are meant to create future income, not just a larger account balance. Employers can help by planting that idea early, in plain terms, shaping how a participant relates to their plan for the rest of their career. -
MID-CAREER
Help employees connect savings to future income
This is the most overlooked stage in participant education, and one of the most important. Workers in their 40s and early 50s are close enough to retirement to grasp the weight of the decision but far enough away to make meaningful adjustments. This is the moment to introduce converting savings into income as a planning horizon: What does your monthly income need to look like in retirement? How much of it do you want guaranteed? Working backward from income targets makes the options concrete and the choices manageable. Plan sponsors can distribute educational materials here tailored to employees to help them understand the changing options. -
LATE CAREER
Enable the shift from accumulation to decumulation
The mental model that serves a saver — grow the balance and ride out volatility — does not carry over to a retiree who has to spend from that balance. Sponsors can help late-career employees make that shift with a simple framework: a target guaranteed income floor, a flexible spending layer and a cushion for unexpected costs. -
AT THE POINT OF RETIREMENT
Decision support
The worst moment to introduce complexity is when a participant is filling out retirement paperwork. By then education has either happened or it hasn’t. The role of plan communication at this stage is to make the right decision the easy one, with clear defaults where appropriate, plain-language summaries of options and a direct path to guidance.
What this means for plan design
Only 37% of plan sponsors say they can clearly articulate the value of annuities to participants.15 That matters because sponsors set the tone for participant education. If the people designing the plan cannot explain how a participant turns savings into guaranteed income, the communications they produce won’t either. A few practical steps can help.
- Start the conversation earlier than feels necessary. Most participant education on income begins too close to retirement, once habits are set and the risk of a rushed, poor decision is high. Introducing income concepts at enrollment, and returning to them at key career milestones, builds the mental scaffolding that makes the retirement decision clearer when it arrives.
- Lead with stories, then support them with data. Bobby’s story works because it doesn’t ask employees to evaluate a product; it asks them to recognize a good outcome. Once they see that outcome as a goal, the product explanation follows naturally.
- Treat the journey as segmented. A single annual email about retirement income reaches everyone equally and no one effectively. Real engagement comes from delivering the right message at the right career stage, with each one building on the last.
Abstract education creates awareness; concrete tools such as income projections, scenario illustrations and clear side-byside comparisons help participants act on it. SECURE 2.0 and the evolving QDIA guidance have given sponsors more design flexibility than they have ever had, and that flexibility becomes valuable once your employees understand what to do with it.17
The case for acting now
Twenty-six percent of retirees say not purchasing an annuity is one of their biggest financial regrets.18 The difficulty is reaching people early enough to act, and before the window closes.
The participants in a plan today still have time to make these decisions. What many of them lack is a plan sponsor who has built the journey, step by step, to get them there.
Bobby Bonilla had an agent who understood the time value of money, the power of guaranteed income and how to negotiate on his client’s behalf. He made one good decision, at the right moment, with the right guidance. Most retirement savers can face a similar choice, provided their plan sponsor has done the work to make each step of the journey clear and simple for them.
The question participants need answered is rarely ‘do I want guaranteed income?’ It is a more layered conversation about savings rates, balances and target income in retirement.
Continue reading
Contact us

- +44 20 3727 8000
- 201 Bishopsgate, London, United Kingdom
Sources
11 Plansponsor. 29 Jun 2026.
12 EBSA, 2025.
13 CNN.com 1 Jul 2025.
14 Plansponsor.com 29 Jun 2026.
15 Napa-net.org 11 Dec 2024.
16 NBER. Apr 2025.
17 Wealthmanagement.com 29 Jun 2026.
18 TIAA.org 18 Dec 2025.
Before investing, carefully consider fund investment objectives, risks, charges and expenses. For this and other information that should be read carefully, please request a prospectus or summary prospectus from your financial professional or Nuveen at 800.257.8787 or visit nuveen.com.
This material is not intended to be a recommendation or investment advice, does not constitute a solicitation to buy, sell or hold a security or investment strategy and is not provided in a fiduciary capacity. The information provided does not take into account the specific objectives or circumstances of any particular investor, or suggest any specific course of action. Investment decisions should be made based on an investor’s objectives and circumstances and in consultation with their financial advisors. Financial professionals should independently evaluate the risks associated with products or services and exercise independent judgment with respect to their clients. This material, along with any views and opinions expressed within, are presented for informational and educational purposes only as of the date of production/writing and may change without notice at any time based on numerous factors, such as changing market, economic, political, or other conditions, legal and regulatory developments, additional risks and uncertainties and may not come to pass. There is no promise, representation, or warranty (express or implied) as to the past, future, or current accuracy, reliability or completeness of, nor liability for, decisions based on such information, and it should not be relied on as such. This material should not be regarded by the recipients as a substitute for the exercise of their own judgment. For index definitions, please visit the glossary on Nuveen.com. Please note it’s not possible to invest in an index directly.
Important information on risk
Past performance is no guarantee of future results. All investments carry a certain degree of risk, including the possible loss of principal, and there is no assurance that an investment will provide positive performance over any period of time. Certain products and services may not be available to all entities or persons. There is no guarantee that investment objectives will be achieved. See the applicable product literature for details.
Investors should be aware that alternative investments are speculative, subject to substantial risks including the risks associated with limited liquidity, the potential use of leverage, potential short sales, currency exchange rates, and concentrated investments and may involve complex tax structures and investment strategies. Alternative investments may be illiquid, there may be no liquid secondary market or ready purchasers for such securities, they may not be required to provide periodic pricing or valuation information to investors, there may be delays in distributing tax information to investors, they are not subject to the same regulatory requirements as other types of pooled investment vehicles, and they may be subject to high fees and expenses, which will reduce profits.