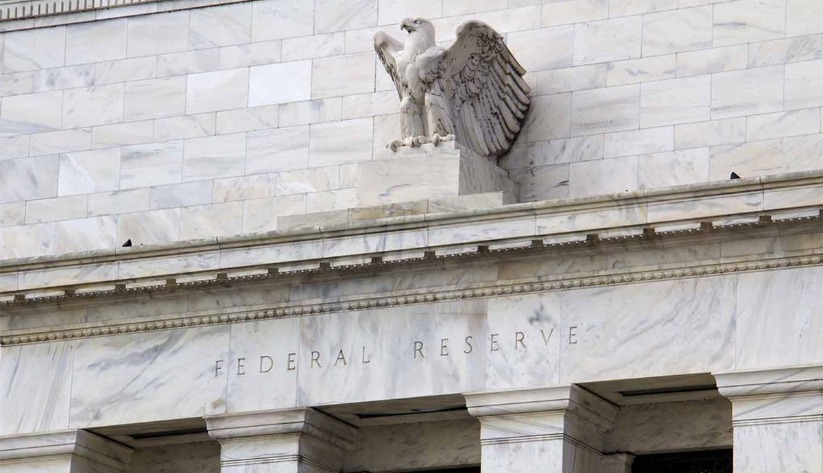
The U.S. Federal Reserve raised rates today for the first time since 2023, navigating inflation risks against a resilient economy. Growth remains solid and the labor market is stabilizing, but concerns that policy remains accommodative pushed the Fed to meet market expectations, hinting at more work to be done. We’re not convinced.
Key takeaways
- The Fed voted unanimously to raise interest rates, with the target policy rate range rising by 25 basis points to 3.75% to 4.00%.
- The policy statement remained brief, with the addition of the assessment that the move would support a “timelier return” to the 2% inflation target.
- Chair Warsh struck an optimistic tone on the economy, acknowledging that more work needs to be on the inflation front. Ongoing geopolitical risks warrant caution, keeping the door open to another hike by year-end, though we remain of the view that this could be a rare one-and-done event.
What happened?
The FOMC voted unanimously to raise rates at its September meeting, bringing the policy rate range to 3.75% to 4.00%. The decisive, dissent-free vote stood in sharp contrast to July, when three regional Fed presidents favored a hike.
The succinct policy statement acknowledged a solid economy, including resilient domestic activity amid elevated uncertainty. The absence of forward guidance was evident with the statement only acknowledging that the move would support a “timelier return” to the 2% target.
The updated Summary of Economic Projections captured a hawkish tilt among Fed members. The median dot plot now shows one additional hike in 2026 followed by no change through next year, removing the rate cut that had previously been embedded.
Accompanying forecast changes were minimal, leaning toward firmer inflation and limited growth upside in 2026.
In the press conference, Chair Warsh struck an optimistic tone on the U.S. economic outlook, pointing to the potential for even stronger growth. He was reluctant to call broad financial conditions as restrictive, instead reiterating that underlying inflation needs to move to 2% clearly and at a sufficient pace, a standard he assessed has not been met yet. That marks a shift from his comments at the last meeting, when he said rising nominal and real yields had done “quite a bit” of the tightening work for the Fed.
The Fed remains firmly out of the forward guidance business. Looking back rather than ahead, Warsh cited three developments since July that warranted "removing a dose of accommodation": a strengthening economy, ongoing geopolitical risks, and insufficient progress on inflation. He downplayed August's inflation data, noting that trends matter more than noisy monthly readings, and said more evidence is needed before considering a pause.
We expect this to be a rare one and done hike, though the hawkish tilt and decisiveness of the decision keep another hike on the table by year-end. Oil prices could prove to be the deciding factor. We still believe inflation should moderate by more than the updated FOMC forecasts imply, while labor markets should remain stable or loosen slightly - easing pressure to tighten further and supporting a steady policy stance. Our year-end forecast is 4.75% for the 10-year Treasury yield.
Fed follows through on an insurance hike
It’s been a volatile stretch since July, marked by rising energy prices amid renewed geopolitical tensions and higher yields from intensifying competition for capital. That backdrop has complicated an otherwise encouraging inflation picture and contributed to today’s move. Even so, we expect stable growth and moderating price pressures through 2027.
We think today’s move is likely a one-and-done rather than the start of a new cycle. August’s hotter-than-expected core CPI and firm PPI pushed markets to nearly fully price in the hike, but there’s limited evidence of a reflating economy. While commodity prices warrant watching, Governor Waller recently noted that a modest uptick in month-on-month inflation wouldn’t necessarily derail disinflationary progress, and core PCE is still tracking below the level he’s flagged as the threshold for further tightening. We don’t think the data justifies the additional hikes markets are pricing in through year-end. Further out, we still see risks skewed toward a 2027 cut, though oil, tariffs, tech spending, and fiscal policy remain swing factors.
Escalating U.S.-Iran tensions have pushed oil and gas prices sharply higher and could be the deciding factor to another rate hike this year. Crude has risen from $84 to $101 since the last Fed meeting, and diesel has broken above $6/gallon for the first time, up from $5.33. While the spillover warrants monitoring, we believe price pressures remain on a moderating path: core services and goods are easing, tariff pass-through is fading and shelter costs are cooling. We forecast core PCE at 3.0% by year-end and 2.4% in 2027, aided by a technical tailwind from the BEA’s September 30 methodology change for software pricing, which should mechanically pull core PCE slightly lower.
Today’s hike is largely about credibility. Chair Warsh has signaled the Fed will defend price stability, and after the recent selloff in long-end Treasuries, policymakers needed to show resolve without validating expectations for a broader tightening cycle. The tone struck roughly that balance: hawkish enough to justify acting on inflation data, not hawkish enough to confirm a hiking cycle anticipated by markets.
A stabilizing labor market gives the Fed more room to focus on inflation. August payrolls rebounded to 162,000 from a revised 21,000 in July, well above the 31,000 average pace of the past year. Unemployment held at 4.1%, participation ticked up and wage growth stayed moderate at 0.3% month-over-month and 3.1% year-over-year, consistent with the Fed’s 2% target. We read this as stabilization rather than reacceleration, and still expect a low-hiring, low-firing dynamic with a small rise in unemployment likely next year.
The Fed’s September projections add context: officials projected 2.3% GDP growth and 3.4% core PCE for 2026, reflecting solid growth alongside a temporary inflation shock, with core PCE expected to fall to 2.5% in 2027 as that shock fades. The updated projections reinforce the picture outlined in June.
We still see a fed funds rate near neutral limiting further moves. Energy risks warrant watching, and upward pressure on yields may persist from fiscal concerns and heavy AI-related issuance. This keeps us cautious on duration and favoring income opportunities in shorter maturities. We now see the 10-year Treasury yield at 4.75% by year-end and 4.50% by end-2027.
What does this mean for investors?
Markets have stayed resilient despite elevated uncertainty, rising yields, and geopolitical tension. Strong earnings support a risk-on posture, but valuations look rich, with the S&P 500’s forward P/E above its long-run average and analysts forecasting double-digit EPS growth, more than triple the 7.5% long-run average. Credit remains tight too, with investment-grade spreads near 80 basis points, tighter than current levels just 4% of the time over the past 25 years. We see this as an opportunity for investors to diversify beyond traditional equity and credit, position for income, and guard against downside risk.
Listed infrastructure looks attractive. The AI boom needs power, and power needs regulated infrastructure to generate and transmit it. Data centers can be built in 12 to 36 months; transmission upgrades and new generation capacity take far longer. That mismatch may create durable scarcity value, and earnings potential, for utilities able to deliver capacity ahead of demand.
As equity portfolios grow more concentrated in the AI trade, listed infrastructure may offer a compelling complement: exposure to the digital economy, anchored in physical assets largely insulated from the technology they power. Infrastructure has long provided defensive diversification against tech, and with the correlation between the two turning negative recently, that benefit has strengthened, offering diversification that’s been hard to find elsewhere in equities.
Preferred securities stand out amid the rate volatility weighing on broader fixed income. Spreads have tightened in both $1,000-par and contingent capital (CoCo) segments, helping drive outperformance versus most U.S. investment-grade sectors this year.
Preferred issuers look fundamentally strong. About 80% of preferred securities come from banks, insurers, and utilities — heavily regulated sectors showing sound fundamentals. Banks have broadly beaten earnings estimates and continued passing Fed stress tests, insurers hold near-record surplus capital and posted record annuity sales, and utilities look well positioned to benefit from AI-driven data center demand and broader electrification.
Technicals support the asset class too. European Additional Tier 1 capital instruments (AT1) CoCo issuers have front-loaded supply, with roughly 80% of full-year volume already issued and well absorbed by the market; supply should moderate in the second half, a tailwind for the sector. Demand remains strong for the tax-advantaged qualified dividend income (QDI) that certain preferred structures offer, while hybrid preferreds remain eligible for corporate bond index inclusion.
Opportunities also exist beyond traditional credit. We favor an integrated approach combining convertible arbitrage, long-short credit, and opportunistic CLO investing, dynamically allocated within a single framework.
Convertible arbitrage anchors this approach. Convertible bonds’ embedded optionality means they benefit from volatility rather than suffer from it, improving returns exactly when traditional strategies struggle. The global convertible market has grown to $600 billion, with liquidity at record levels, offering a deep and diverse opportunity set.
Long-short credit adds flexibility. By taking both long and short positions across high-yield bonds and senior loans, including distressed situations and tactical hedges, this component seeks alpha while while actively managing downside, a dynamic tool for navigating cyclical turns rather than a passive bet on spreads.
Opportunistic CLO debt and equity investing completes the framework. High-conviction positions in structured credit, deployed selectively when valuations compel, can offer a differentiated return stream with low correlation to the other two strategies, enhancing diversification.
Together, we believe these three strategies aim to navigate different market environments, with the potential for attractive risk-adjusted returns, enhanced resilience during market downturns, and additional diversification relative to both equities and traditional credit. Investors who incorporate this multi-strategy approach may be better prepared to respond to evolving market conditions.
Featured insights

Opportunity grows for senior loans and CLOs
Alternatives in a new world order
Contact us

- +44 20 3727 8000
- 201 Bishopsgate, London, United Kingdom
Endnotes
Sources
Federal Reserve Statement, September 2026.
Bloomberg, L.P., S&P Markit.
This material is not intended to be a recommendation or investment advice, does not constitute a solicitation buy, sell or hold a security or an investment strategy, and is not provided in a fiduciary capacity. The information provided does not take into account the specific objectives or circumstances of any particular investor, or suggest any specific course of action. Investment decisions should be made based on an investor’s objectives and circumstances and in consultation with his or her financial professionals.
The views and opinions expressed are for informational and educational purposes only as of the date of production/writing and may change without notice at any time based on numerous factors, such as market or other conditions, legal and regulatory developments, additional risks and uncertainties and may not come to pass. This material may contain “forward-looking” information that is not purely historical in nature. Such information may include, among other things, projections, forecasts, estimates of market returns, and proposed or expected portfolio composition. Any changes to assumptions that may have been made in preparing this material could have a material impact on the information presented herein by way of example. Performance data shown represents past performance and does not predict or guarantee future results. Investing involves risk; principal loss is possible.
All information has been obtained from sources believed to be reliable, but its accuracy is not guaranteed. There is no representation or warranty as to the current accuracy, reliability or completeness of, nor liability for, decisions based on such information and it should not be relied on as such. For term definitions and index descriptions, please access the glossary on nuveen.com. Please note, it is not possible to invest directly in an index.
Important information on risk
All investments carry a certain degree of risk and there is no assurance that an investment will provide positive performance over any period of time. Equity investing involves risk. Investments are also subject to political, currency and regulatory risks. These risks may be magnified in emerging markets. Diversification is a technique to help reduce risk. There is no guarantee that diversification will protect against a loss of income.
Debt or fixed income securities are subject to market risk, credit risk, interest rate risk, call risk, derivatives risk, dollar roll transaction risk and income risk. As interest rates rise, bond prices fall. Investing in municipal bonds involves risks such as interest rate risk, credit risk and market risk, including the possible loss of principal. The value of the portfolio will fluctuate based on the value of the underlying securities. There are special risks associated with investments in high yield bonds, hedging activities and the potential use of leverage. Portfolios that include lower rated municipal bonds, commonly referred to as “high yield” or “junk” bonds, which are considered to be speculative, the credit and investment risk is heightened for the portfolio. Credit ratings are subject to change. AAA, AA, A, and BBB are investment grade ratings; BB, B, CCC/CC/C and D are below-investment grade ratings.
Preferred securities are subordinate to bonds and other debt instruments in a company’s capital structure and therefore are subject to greater credit risk. Certain types of preferred, hybrid or debt securities with special loss absorption provisions, such as contingent capital securities (CoCos), may be or become so subordinated that they present risks equivalent to, or in some cases even greater than, the same company’s common stock.
Concentration in infrastructure-related securities involves sector risk and concentration risk, particularly greater exposure to adverse economic, regulatory, political, legal, liquidity, and tax risks associated with MLPs and REITs.
Convertible arbitrage involves significant risks, including the potential for loss on both long convertible security positions and short equity positions if the anticipated pricing relationship between the two does not perform as expected. These strategies may employ leverage, which can magnify losses, and are subject to liquidity, credit, and market volatility risks that may be heightened during periods of market stress. Below investment grade or high yield debt securities are subject to heightened credit risk, liquidity risk and potential for default. These securities, while generally offering higher yields than investment grade debt with similar maturities, involve greater risks, including the possibility of interest deferral, default or bankruptcy, and are regarded as predominantly speculative with respect to the issuer’s capacity to pay dividends or interest and repay principal. Issuers of high yield securities may be highly leveraged and may have fewer methods of financing available. The prices of these lower-grade securities are typically more sensitive to negative developments, such as a decline in the issuer’s revenues or a general economic downturn, than are the prices of higher-grade securities. The secondary market for high yield securities may not be as liquid as the secondary market for more highly rated securities, a factor which may have an adverse effect on a portfolio’s ability to dispose of a particular security. There are fewer dealers in the market for high yield securities than for investment grade obligations. Any investment in collateralized loan obligations or other structured vehicles involves significant risks not associated with more conventional investment alternatives.
Nuveen, LLC provides investment solutions through its investment specialists.
This information does not constitute investment research as defined under MiFID.